Prior APA methodology guides transfer pricing benchmarking where consistent FAR profiles support comparability and arm's length margins eliminate adju...
Battery-integrated tablet rear covers classify as lithium-ion accumulators when protective components enable the battery's active energy-storage funct...
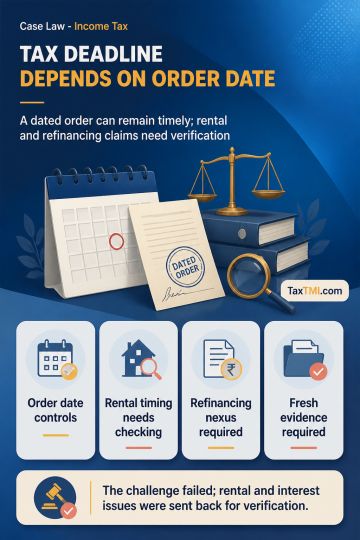
Assessment-order limitation depends on when the order is made or passed within the statutory period, not on later dispatch, communication or receipt; a dated order remains timely absent material showing it was actually made later. Rental income reflected in Form 26AS cannot be added without verifying whether timing differences from straight-line lease-rental recognition have already been taxed in another year. Interest on refinancing may qualify for deduction under section 24(b) only where a direct nexus connects the original borrowing, property acquisition or construction, and subsequent loan. Tenant-wise reconciliation and refinancing fund-flow evidence require fresh verification; the limitation challenge was rejected, while the rental and interest issues were remanded.
Assessment-order limitation depends on when the order is made or passed within the statutory period, not on later dispatch, communication or receipt; a dated order remains timely absent material showing it was actually made later. Rental income reflected in Form 26AS cannot be added without verifying whether timing differences from straight-line lease-rental recognition have already been taxed in another year. Interest on refinancing may qualify for deduction under section 24(b) only where a direct nexus connects the original borrowing, property acquisition or construction, and subsequent loan. Tenant-wise reconciliation and refinancing fund-flow evidence require fresh verification; the limitation challenge was rejected, while the rental and interest issues were remanded.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881