Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Page of 4881
Press 'Enter' after typing page number.
781 to 800 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
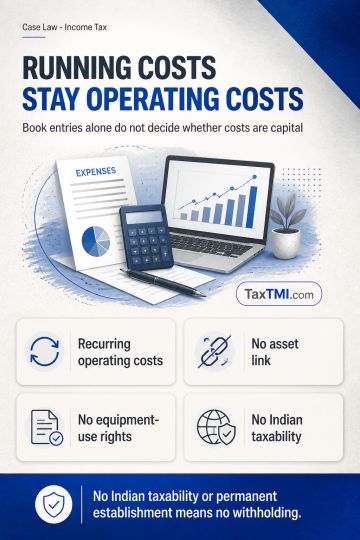
Operational expenditure incurred to run an already deployed, revenue-generating telecom network retains its revenue character even when recorded as capital work-in-progress; book entries do not conclusively determine tax deductibility. Absent identification of an asset created or a nexus with acquisition or construction, deferral until quality-of-service targets are met does not make recurring operating costs capital. Payments to non-resident telecom operators for connectivity, carriage, termination, bandwidth and maintenance are not royalty or technical-service fees where the payer obtains no right to use equipment or process and receives no technical capability. Without Indian taxability or a permanent establishment, no withholding obligation arises.
Operational expenditure incurred to run an already deployed, revenue-generating telecom network retains its revenue character even when recorded as capital work-in-progress; book entries do not conclusively determine tax deductibility. Absent identification of an asset created or a nexus with acquisition or construction, deferral until quality-of-service targets are met does not make recurring operating costs capital. Payments to non-resident telecom operators for connectivity, carriage, termination, bandwidth and maintenance are not royalty or technical-service fees where the payer obtains no right to use equipment or process and receives no technical capability. Without Indian taxability or a permanent establishment, no withholding obligation arises.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881