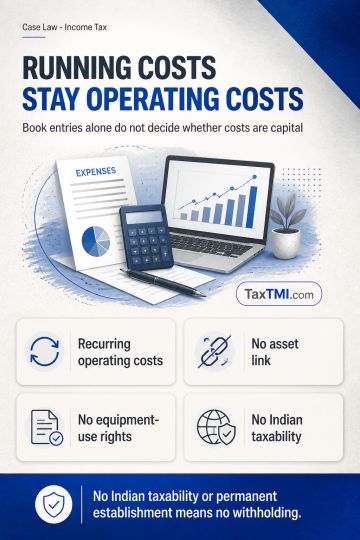
Operational expenditure incurred to run an already deployed, revenue-generating telecom network retains its revenue character even when recorded as capital work-in-progress; book entries do not conclusively determine tax deductibility. Absent identification of an asset created or a nexus with acquisition or construction, deferral until quality-of-service targets are met does not make recurring operating costs capital. Payments to non-resident telecom operators for connectivity, carriage, termination, bandwidth and maintenance are not royalty or technical-service fees where the payer obtains no right to use equipment or process and receives no technical capability. Without Indian taxability or a permanent establishment, no withholding obligation arises.
Operational expenditure incurred to run an already deployed, revenue-generating telecom network retains its revenue character even when recorded as capital work-in-progress; book entries do not conclusively determine tax deductibility. Absent identification of an asset created or a nexus with acquisition or construction, deferral until quality-of-service targets are met does not make recurring operating costs capital. Payments to non-resident telecom operators for connectivity, carriage, termination, bandwidth and maintenance are not royalty or technical-service fees where the payer obtains no right to use equipment or process and receives no technical capability. Without Indian taxability or a permanent establishment, no withholding obligation arises.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI