Concessional corporate tax option under section 115BAA survives procedural documentary lapses when statutory compliance and earlier exercise are estab...
Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
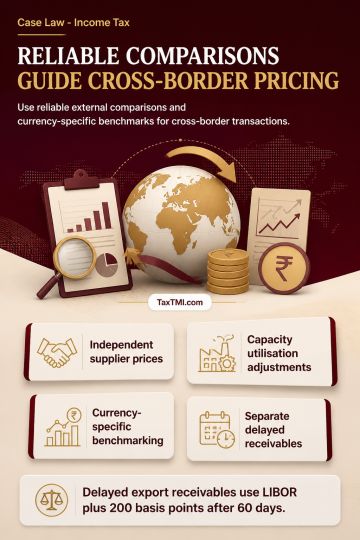
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
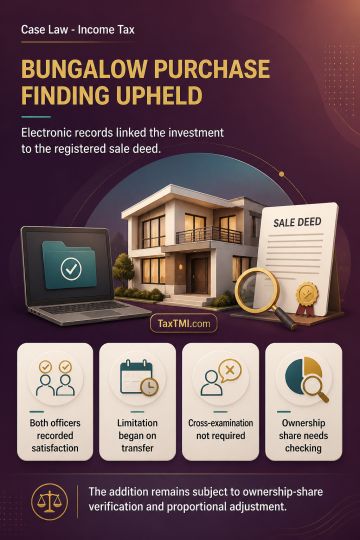
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
Availability of a statutory appellate remedy against GST registration cancellation and rejection of revocation ordinarily precludes adjudication of factual disputes in writ jurisdiction. Appeals lay against both orders; therefore, factual contentions remained open for determination by the appellate authority. Where the revocation-rejection order was undated but served on 22 August 2026, the service date was directed to be treated as the order date for pursuing the appellate remedy. The taxpayer was permitted to file appeals against both orders within two weeks, for expeditious disposal.
Availability of a statutory appellate remedy against GST registration cancellation and rejection of revocation ordinarily precludes adjudication of factual disputes in writ jurisdiction. Appeals lay against both orders; therefore, factual contentions remained open for determination by the appellate authority. Where the revocation-rejection order was undated but served on 22 August 2026, the service date was directed to be treated as the order date for pursuing the appellate remedy. The taxpayer was permitted to file appeals against both orders within two weeks, for expeditious disposal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908