Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
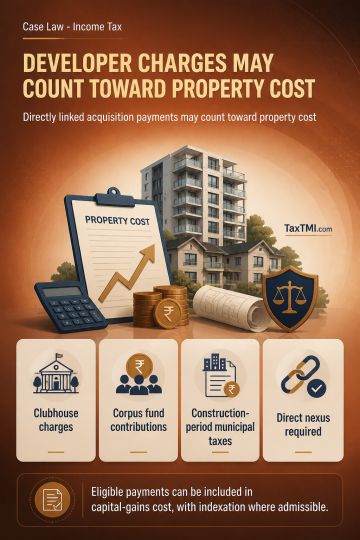
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
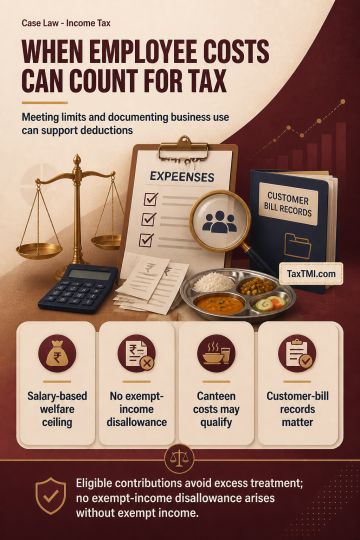
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
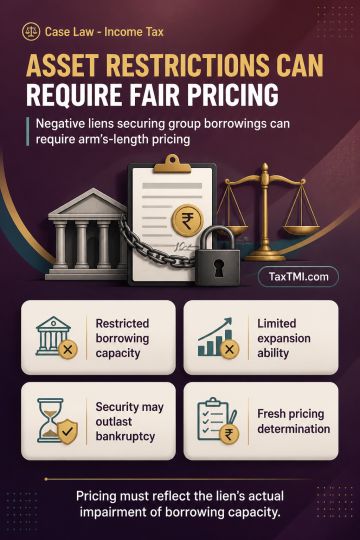
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
Availability of a statutory appellate remedy against GST registration cancellation and rejection of revocation ordinarily precludes adjudication of factual disputes in writ jurisdiction. Appeals lay against both orders; therefore, factual contentions remained open for determination by the appellate authority. Where the revocation-rejection order was undated but served on 22 August 2026, the service date was directed to be treated as the order date for pursuing the appellate remedy. The taxpayer was permitted to file appeals against both orders within two weeks, for expeditious disposal.
Availability of a statutory appellate remedy against GST registration cancellation and rejection of revocation ordinarily precludes adjudication of factual disputes in writ jurisdiction. Appeals lay against both orders; therefore, factual contentions remained open for determination by the appellate authority. Where the revocation-rejection order was undated but served on 22 August 2026, the service date was directed to be treated as the order date for pursuing the appellate remedy. The taxpayer was permitted to file appeals against both orders within two weeks, for expeditious disposal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899