Ratification of resignation acceptance validates separation retrospectively, while withdrawal may be refused through reasoned administrative discretio...
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements fr...
Alternative GST remedy permitted protective writ intervention for ex parte adjudication, preserving independent appellate review of input tax credit d...
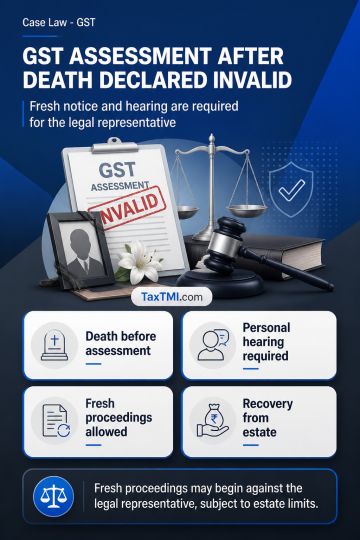
Assessment against deceased sole proprietor requires proceedings against the legal representative, rendering prior assessment and appellate orders inv...
Residential waste collection classification under SAC 999423 defeats composite-supply exemption where facilitating goods are not transferred to the lo...
Page of 4915
Press 'Enter' after typing page number.
2461 to 2480 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Availability of a statutory appellate remedy against GST registration cancellation and rejection of revocation ordinarily precludes adjudication of factual disputes in writ jurisdiction. Appeals lay against both orders; therefore, factual contentions remained open for determination by the appellate authority. Where the revocation-rejection order was undated but served on 22 August 2026, the service date was directed to be treated as the order date for pursuing the appellate remedy. The taxpayer was permitted to file appeals against both orders within two weeks, for expeditious disposal.
Availability of a statutory appellate remedy against GST registration cancellation and rejection of revocation ordinarily precludes adjudication of factual disputes in writ jurisdiction. Appeals lay against both orders; therefore, factual contentions remained open for determination by the appellate authority. Where the revocation-rejection order was undated but served on 22 August 2026, the service date was directed to be treated as the order date for pursuing the appellate remedy. The taxpayer was permitted to file appeals against both orders within two weeks, for expeditious disposal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915