Concessional corporate tax option under section 115BAA survives procedural documentary lapses when statutory compliance and earlier exercise are estab...
Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
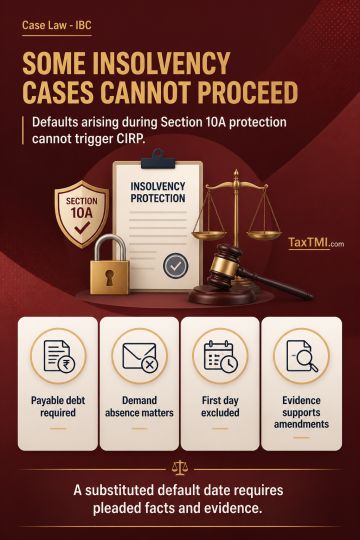
Section 10A bars CIRP for defaults arising during its protected period. A cash-credit default requires non-payment of a debt that is legally due and presently payable; deferred interest recovery and the absence of a demand under an on-demand facility may prevent an actionable default. For an ad hoc cash-credit facility, a repayment period running from the date of availment excludes that first day, so default arises only after the period expires. Amendment of a Section 7 application may be permitted, but a substituted default date must be supported by pleaded facts and evidence, particularly where Section 10A permanently affects maintainability.
Section 10A bars CIRP for defaults arising during its protected period. A cash-credit default requires non-payment of a debt that is legally due and presently payable; deferred interest recovery and the absence of a demand under an on-demand facility may prevent an actionable default. For an ad hoc cash-credit facility, a repayment period running from the date of availment excludes that first day, so default arises only after the period expires. Amendment of a Section 7 application may be permitted, but a substituted default date must be supported by pleaded facts and evidence, particularly where Section 10A permanently affects maintainability.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891