Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
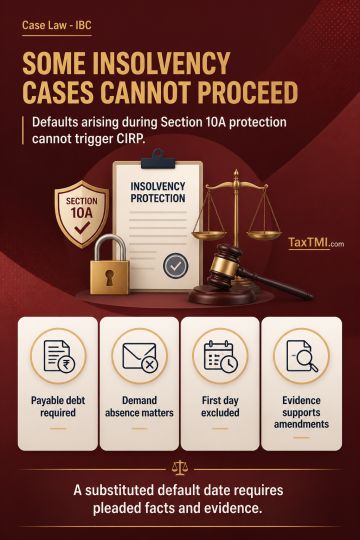
Section 10A bars CIRP for defaults arising during its protected period. A cash-credit default requires non-payment of a debt that is legally due and presently payable; deferred interest recovery and the absence of a demand under an on-demand facility may prevent an actionable default. For an ad hoc cash-credit facility, a repayment period running from the date of availment excludes that first day, so default arises only after the period expires. Amendment of a Section 7 application may be permitted, but a substituted default date must be supported by pleaded facts and evidence, particularly where Section 10A permanently affects maintainability.
Section 10A bars CIRP for defaults arising during its protected period. A cash-credit default requires non-payment of a debt that is legally due and presently payable; deferred interest recovery and the absence of a demand under an on-demand facility may prevent an actionable default. For an ad hoc cash-credit facility, a repayment period running from the date of availment excludes that first day, so default arises only after the period expires. Amendment of a Section 7 application may be permitted, but a substituted default date must be supported by pleaded facts and evidence, particularly where Section 10A permanently affects maintainability.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI