Actual-user customs exemption conditions permit turnkey project transfers when imported windmill components are exclusively used for installation and ...
Customs offence disqualification excludes civil contraventions, preventing refusal of a private bonded warehouse licence based solely on monetary pena...
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Page of 4896
Press 'Enter' after typing page number.
701 to 720 of 97907 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
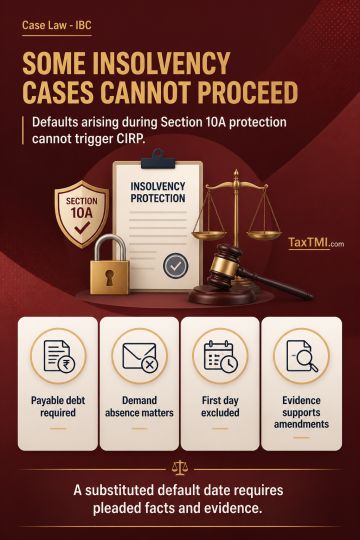
Section 10A bars CIRP for defaults arising during its protected period. A cash-credit default requires non-payment of a debt that is legally due and presently payable; deferred interest recovery and the absence of a demand under an on-demand facility may prevent an actionable default. For an ad hoc cash-credit facility, a repayment period running from the date of availment excludes that first day, so default arises only after the period expires. Amendment of a Section 7 application may be permitted, but a substituted default date must be supported by pleaded facts and evidence, particularly where Section 10A permanently affects maintainability.
Section 10A bars CIRP for defaults arising during its protected period. A cash-credit default requires non-payment of a debt that is legally due and presently payable; deferred interest recovery and the absence of a demand under an on-demand facility may prevent an actionable default. For an ad hoc cash-credit facility, a repayment period running from the date of availment excludes that first day, so default arises only after the period expires. Amendment of a Section 7 application may be permitted, but a substituted default date must be supported by pleaded facts and evidence, particularly where Section 10A permanently affects maintainability.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896