Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
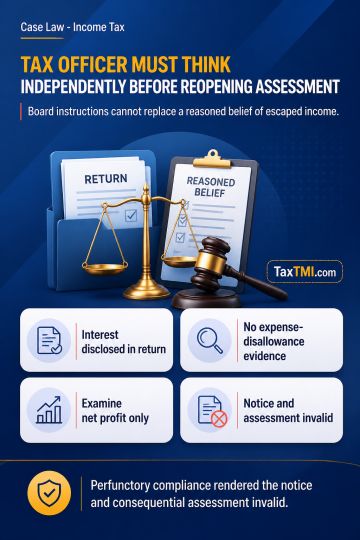
Independent satisfaction of the Assessing Officer is required before reassessment can be initiated; a Board instruction cannot substitute for a reasoned belief that income escaped assessment. Where interest income was disclosed in a return, even if the return was treated as invalid, and no material shows that related expenses were wrongly claimed or disallowable, the available material may justify examination of net profit only. It does not support treating the entire interest income as escaped. Reassessment reasons reflecting only perfunctory compliance with directions therefore lack the required basis, rendering the notice and consequential assessment invalid.
Independent satisfaction of the Assessing Officer is required before reassessment can be initiated; a Board instruction cannot substitute for a reasoned belief that income escaped assessment. Where interest income was disclosed in a return, even if the return was treated as invalid, and no material shows that related expenses were wrongly claimed or disallowable, the available material may justify examination of net profit only. It does not support treating the entire interest income as escaped. Reassessment reasons reflecting only perfunctory compliance with directions therefore lack the required basis, rendering the notice and consequential assessment invalid.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI