Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
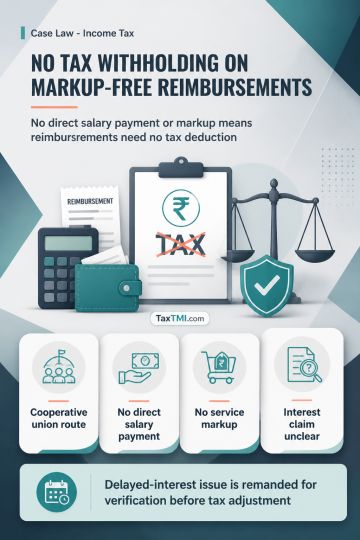
Salary reimbursements paid through an apex cooperative union for deputed supervisory staff do not require tax deduction at source where the assessee makes no direct salary payment and the remittance contains no service markup. In those circumstances, disallowance for non-deduction of tax under section 40(a)(ia) does not arise. Interest for delayed deposit of TDS under section 201(1A) cannot be disallowed unless it has been claimed as an expenditure deduction. Verification is required where it is unclear whether that interest was claimed; the interest issue is remanded for this factual verification.
Salary reimbursements paid through an apex cooperative union for deputed supervisory staff do not require tax deduction at source where the assessee makes no direct salary payment and the remittance contains no service markup. In those circumstances, disallowance for non-deduction of tax under section 40(a)(ia) does not arise. Interest for delayed deposit of TDS under section 201(1A) cannot be disallowed unless it has been claimed as an expenditure deduction. Verification is required where it is unclear whether that interest was claimed; the interest issue is remanded for this factual verification.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI