Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
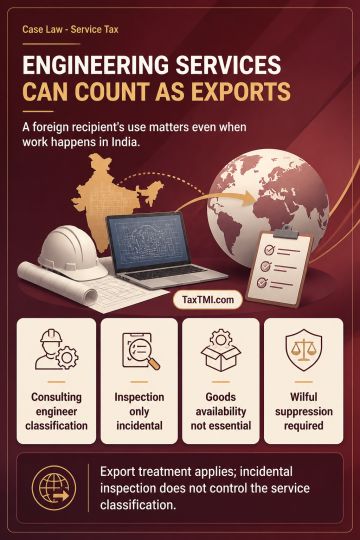
Composite engineering assignments involving drawing assistance, development, technical clarification, material specifications, quality coordination and dispatch assistance are classifiable by their essential character as Consulting Engineer Service, rather than Technical Inspection and Certification Service where inspection is only incidental and independently uncharged. Services supplied to a foreign contractual recipient for convertible foreign exchange qualify as exports where the recipient is the user; physical performance in India does not displace export treatment. From 1 July 2012, the physical-availability-of-goods rule applies only when goods must be physically available to provide the service, so the foreign recipient's location governs otherwise. Extended limitation requires wilful suppression or contravention with intent to evade tax and cannot rest on a later departmental view after relevant disclosures.
Composite engineering assignments involving drawing assistance, development, technical clarification, material specifications, quality coordination and dispatch assistance are classifiable by their essential character as Consulting Engineer Service, rather than Technical Inspection and Certification Service where inspection is only incidental and independently uncharged. Services supplied to a foreign contractual recipient for convertible foreign exchange qualify as exports where the recipient is the user; physical performance in India does not displace export treatment. From 1 July 2012, the physical-availability-of-goods rule applies only when goods must be physically available to provide the service, so the foreign recipient's location governs otherwise. Extended limitation requires wilful suppression or contravention with intent to evade tax and cannot rest on a later departmental view after relevant disclosures.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888