Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
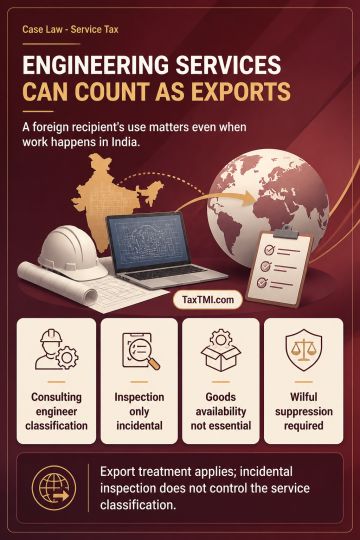
Composite engineering assignments involving drawing assistance, development, technical clarification, material specifications, quality coordination and dispatch assistance are classifiable by their essential character as Consulting Engineer Service, rather than Technical Inspection and Certification Service where inspection is only incidental and independently uncharged. Services supplied to a foreign contractual recipient for convertible foreign exchange qualify as exports where the recipient is the user; physical performance in India does not displace export treatment. From 1 July 2012, the physical-availability-of-goods rule applies only when goods must be physically available to provide the service, so the foreign recipient's location governs otherwise. Extended limitation requires wilful suppression or contravention with intent to evade tax and cannot rest on a later departmental view after relevant disclosures.
Composite engineering assignments involving drawing assistance, development, technical clarification, material specifications, quality coordination and dispatch assistance are classifiable by their essential character as Consulting Engineer Service, rather than Technical Inspection and Certification Service where inspection is only incidental and independently uncharged. Services supplied to a foreign contractual recipient for convertible foreign exchange qualify as exports where the recipient is the user; physical performance in India does not displace export treatment. From 1 July 2012, the physical-availability-of-goods rule applies only when goods must be physically available to provide the service, so the foreign recipient's location governs otherwise. Extended limitation requires wilful suppression or contravention with intent to evade tax and cannot rest on a later departmental view after relevant disclosures.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI