Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Development rights transfers treated as immovable property, while construction abatement applies and repeated non-payment permits extended service-tax...
Page of 12
Press 'Enter' after typing page number.
1 to 20 of 223 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
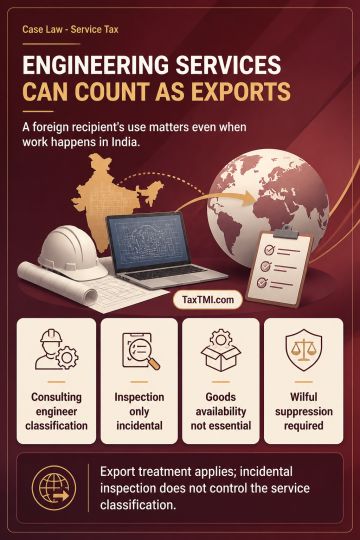
Composite engineering assignments involving drawing assistance, development, technical clarification, material specifications, quality coordination and dispatch assistance are classifiable by their essential character as Consulting Engineer Service, rather than Technical Inspection and Certification Service where inspection is only incidental and independently uncharged. Services supplied to a foreign contractual recipient for convertible foreign exchange qualify as exports where the recipient is the user; physical performance in India does not displace export treatment. From 1 July 2012, the physical-availability-of-goods rule applies only when goods must be physically available to provide the service, so the foreign recipient's location governs otherwise. Extended limitation requires wilful suppression or contravention with intent to evade tax and cannot rest on a later departmental view after relevant disclosures.
Composite engineering assignments involving drawing assistance, development, technical clarification, material specifications, quality coordination and dispatch assistance are classifiable by their essential character as Consulting Engineer Service, rather than Technical Inspection and Certification Service where inspection is only incidental and independently uncharged. Services supplied to a foreign contractual recipient for convertible foreign exchange qualify as exports where the recipient is the user; physical performance in India does not displace export treatment. From 1 July 2012, the physical-availability-of-goods rule applies only when goods must be physically available to provide the service, so the foreign recipient's location governs otherwise. Extended limitation requires wilful suppression or contravention with intent to evade tax and cannot rest on a later departmental view after relevant disclosures.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI