Concessional penalty for search-disclosed unreconciled jewellery applies where substantive disclosure conditions are met despite omission from origina...
Alternative statutory remedy and unexplained delay barred writ review of customs confiscation adjudication, leaving merits for appellate consideration...
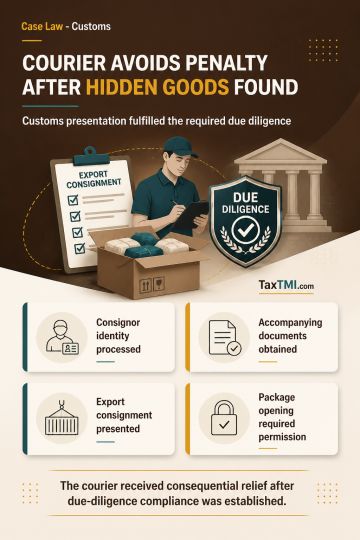
Authorised courier due diligence protects against penalties where declared exports conceal prohibited goods despite proper documentation and customs p...
Commercially genuine exclusivity payments, transition-fee reimbursements and upfront discounts made to associated enterprises cannot be disregarded merely because their commercial structure is unusual or their expediency is questioned. Arm's length pricing cannot be fixed at nil without applying a prescribed transfer-pricing method; where the underlying primary adjustment fails, consequential notional interest also fails. Secondary-adjustment provisions do not apply to primary adjustments preceding 1 April 2016. Interest on a foreign-currency associated-enterprise loan is benchmarked at LIBOR plus 80 basis points. For exempt-income disallowance, only income-yielding investments are relevant and sufficient own interest-free funds preclude interest disallowance. Export turnover, TDS credit and education-cess claims were addressed through specified computation, verification and retrospective-amendment principles.
Commercially genuine exclusivity payments, transition-fee reimbursements and upfront discounts made to associated enterprises cannot be disregarded merely because their commercial structure is unusual or their expediency is questioned. Arm's length pricing cannot be fixed at nil without applying a prescribed transfer-pricing method; where the underlying primary adjustment fails, consequential notional interest also fails. Secondary-adjustment provisions do not apply to primary adjustments preceding 1 April 2016. Interest on a foreign-currency associated-enterprise loan is benchmarked at LIBOR plus 80 basis points. For exempt-income disallowance, only income-yielding investments are relevant and sufficient own interest-free funds preclude interest disallowance. Export turnover, TDS credit and education-cess claims were addressed through specified computation, verification and retrospective-amendment principles.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888