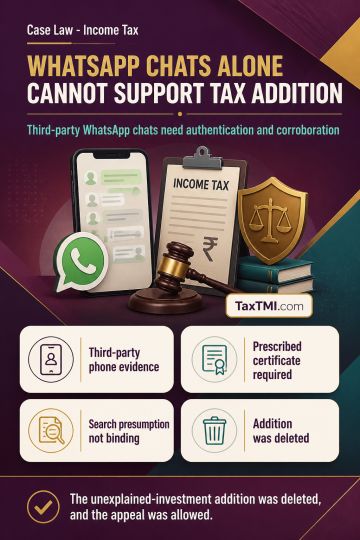
Electronic WhatsApp evidence without authentication or independent corroboration cannot sustain an unexplained-investment addition based on third-part...
Page of 4888
Press 'Enter' after typing page number.
1381 to 1400 of 97750 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Rule 86A permits restriction on debit of input tax credit in an electronic credit ledger only when its prescribed conditions are met, including recorded reasons to believe and reasons in writing. The High Court found that the authorities could not establish compliance with these mandatory requirements before blocking the ledger. As the statutory period had expired and the ledger had been reactivated, the writ petition was disposed of exceptionally upon acceptance of an unconditional apology. The High Court warned that any future non-compliant blocking of credit would expose the authorities to appropriate compensation liability.
Rule 86A permits restriction on debit of input tax credit in an electronic credit ledger only when its prescribed conditions are met, including recorded reasons to believe and reasons in writing. The High Court found that the authorities could not establish compliance with these mandatory requirements before blocking the ledger. As the statutory period had expired and the ledger had been reactivated, the writ petition was disposed of exceptionally upon acceptance of an unconditional apology. The High Court warned that any future non-compliant blocking of credit would expose the authorities to appropriate compensation liability.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888