Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
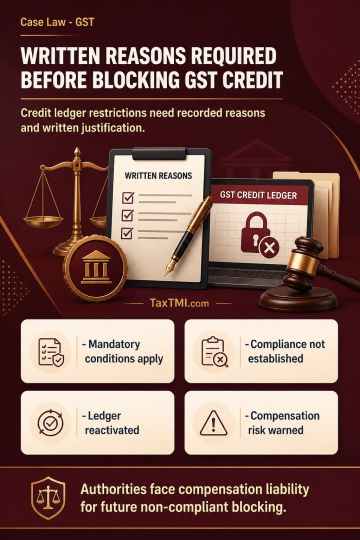
Rule 86A permits restriction on debit of input tax credit in an electronic credit ledger only when its prescribed conditions are met, including recorded reasons to believe and reasons in writing. The High Court found that the authorities could not establish compliance with these mandatory requirements before blocking the ledger. As the statutory period had expired and the ledger had been reactivated, the writ petition was disposed of exceptionally upon acceptance of an unconditional apology. The High Court warned that any future non-compliant blocking of credit would expose the authorities to appropriate compensation liability.
Rule 86A permits restriction on debit of input tax credit in an electronic credit ledger only when its prescribed conditions are met, including recorded reasons to believe and reasons in writing. The High Court found that the authorities could not establish compliance with these mandatory requirements before blocking the ledger. As the statutory period had expired and the ledger had been reactivated, the writ petition was disposed of exceptionally upon acceptance of an unconditional apology. The High Court warned that any future non-compliant blocking of credit would expose the authorities to appropriate compensation liability.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI