Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Page of 4916
Press 'Enter' after typing page number.
41 to 60 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
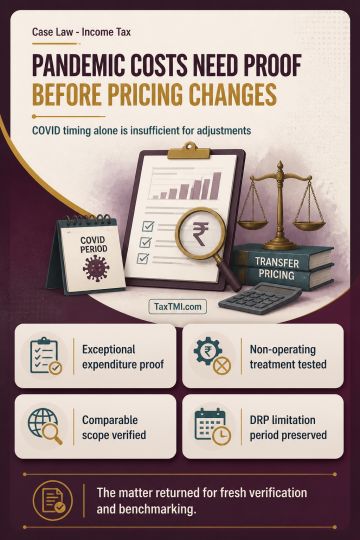
COVID-19 adjustments in transfer-pricing benchmarking require proof of exceptional pandemic expenditure, its non-operating character, and a materially different impact on comparables; pandemic timing alone is insufficient. TNMM also requires consistent treatment of operating and non-operating items for the tested party and comparables, including foreign-exchange effects from revenue transactions and depreciation on business assets. Internal CUP for software support services requires transaction-level comparability of contractual scope, functions, assets, risks, personnel, volume, duration and market conditions, with reliable adjustments for material differences. Transfer-pricing adjustments were remanded for fresh verification and benchmarking. A final assessment following timely draft assessment and DRP directions remains within the separate DRP-related limitation period.
COVID-19 adjustments in transfer-pricing benchmarking require proof of exceptional pandemic expenditure, its non-operating character, and a materially different impact on comparables; pandemic timing alone is insufficient. TNMM also requires consistent treatment of operating and non-operating items for the tested party and comparables, including foreign-exchange effects from revenue transactions and depreciation on business assets. Internal CUP for software support services requires transaction-level comparability of contractual scope, functions, assets, risks, personnel, volume, duration and market conditions, with reliable adjustments for material differences. Transfer-pricing adjustments were remanded for fresh verification and benchmarking. A final assessment following timely draft assessment and DRP directions remains within the separate DRP-related limitation period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916