Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
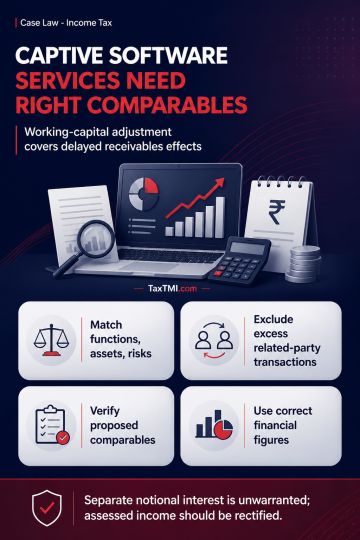
Captive contract software-development services are benchmarked against companies performing comparable software-development functions, assets and risks; product-development businesses, complex digital-product providers and companies lacking relevant segmental information are unsuitable. Companies earning software-development service revenue may remain comparable where no material functional difference is established, while entities exceeding the applicable related-party transaction filter must be excluded. Where delayed trade receivables arise solely from the service transaction benchmarked under TNMM, they require combined benchmarking. Working-capital adjustment for material differences subsumes the receivables effect, so separate notional interest is unwarranted. Financials of an unverified proposed comparable require verification against applicable filters, and assessed income should be rectified using correct figures.
Captive contract software-development services are benchmarked against companies performing comparable software-development functions, assets and risks; product-development businesses, complex digital-product providers and companies lacking relevant segmental information are unsuitable. Companies earning software-development service revenue may remain comparable where no material functional difference is established, while entities exceeding the applicable related-party transaction filter must be excluded. Where delayed trade receivables arise solely from the service transaction benchmarked under TNMM, they require combined benchmarking. Working-capital adjustment for material differences subsumes the receivables effect, so separate notional interest is unwarranted. Financials of an unverified proposed comparable require verification against applicable filters, and assessed income should be rectified using correct figures.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI