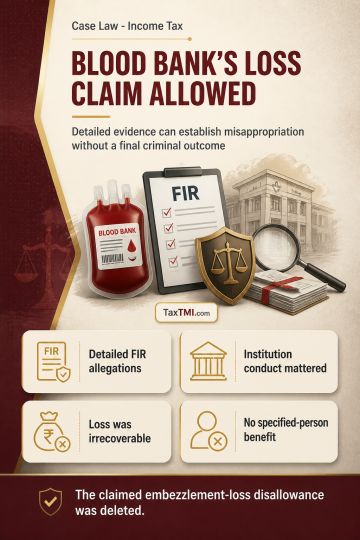
Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
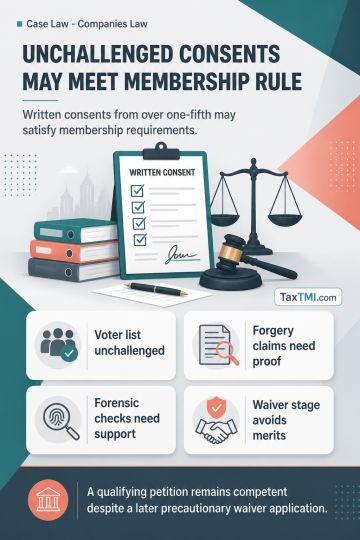
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
Transfer-pricing benchmarking requires exclusion of comparables...
Transfer-pricing comparability requires exclusion of financially illogical super-profit comparables and correction of unsupported annual-report and margin findings.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Transfer-pricing benchmarking requires exclusion of comparables with financially illogical gross-profit-to-sales ratios of 100 per cent or more, applying the principle that super-profit-making companies should not be retained for comparability analysis. The inclusion of four such entities was set aside and remitted to the TPO for fresh consideration after hearing the assessee. A comparable could not be rejected for non-availability of its annual report where that report had been furnished to the TPO; its inclusion in the benchmarking exercise was directed. The TPO's positive gross-profit-margin computation for another comparable was also found erroneous because the record showed a negative margin, requiring fresh determination.
Transfer-pricing benchmarking requires exclusion of comparables with financially illogical gross-profit-to-sales ratios of 100 per cent or more, applying the principle that super-profit-making companies should not be retained for comparability analysis. The inclusion of four such entities was set aside and remitted to the TPO for fresh consideration after hearing the assessee. A comparable could not be rejected for non-availability of its annual report where that report had been furnished to the TPO; its inclusion in the benchmarking exercise was directed. The TPO's positive gross-profit-margin computation for another comparable was also found erroneous because the record showed a negative margin, requiring fresh determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927