Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements fr...
Page of 7
Press 'Enter' after typing page number.
1 to 20 of 140 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
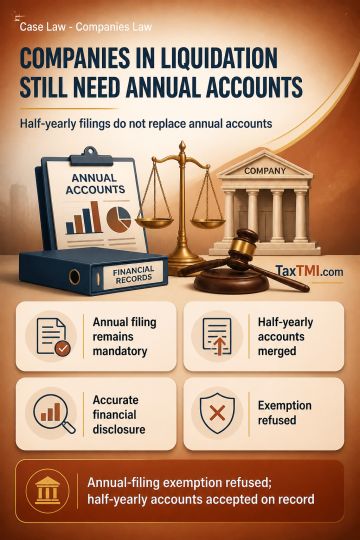
Companies in liquidation must file annual or final accounts even where audited half-yearly accounts for both halves of the financial year have been filed. Half-yearly accounts must be merged into annual accounts because annual reporting is necessary to accurately disclose the companies' financial position. Exemption from filing annual or final accounts for the relevant financial year was therefore refused. The half-yearly accounts were accepted on record, and auditors' fees could be paid from available company funds or, subject to reimbursement, from the Estate and Establishment Fund.
Companies in liquidation must file annual or final accounts even where audited half-yearly accounts for both halves of the financial year have been filed. Half-yearly accounts must be merged into annual accounts because annual reporting is necessary to accurately disclose the companies' financial position. Exemption from filing annual or final accounts for the relevant financial year was therefore refused. The half-yearly accounts were accepted on record, and auditors' fees could be paid from available company funds or, subject to reimbursement, from the Estate and Establishment Fund.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI