Electronic WhatsApp evidence without authentication or independent corroboration cannot sustain an unexplained-investment addition based on third-part...
Page of 4886
Press 'Enter' after typing page number.
1341 to 1360 of 97710 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
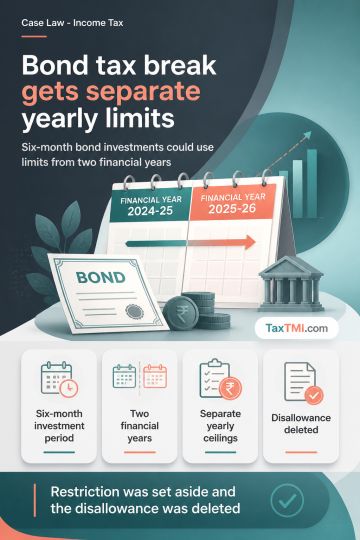
Section 54EC exemption for long-term capital gains may apply where specified bonds are purchased within six months of transfer across two financial years. For Assessment Year 2013-14, the investment ceiling operated independently for each financial year when the six-month period overlapped them, rather than as a single transaction-wide cap. The later amendment imposing an aggregate cap for the year of transfer and the succeeding financial year did not apply. Accordingly, restricting the exemption to one financial year's ceiling was set aside and the disallowance was deleted.
Section 54EC exemption for long-term capital gains may apply where specified bonds are purchased within six months of transfer across two financial years. For Assessment Year 2013-14, the investment ceiling operated independently for each financial year when the six-month period overlapped them, rather than as a single transaction-wide cap. The later amendment imposing an aggregate cap for the year of transfer and the succeeding financial year did not apply. Accordingly, restricting the exemption to one financial year's ceiling was set aside and the disallowance was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886