Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
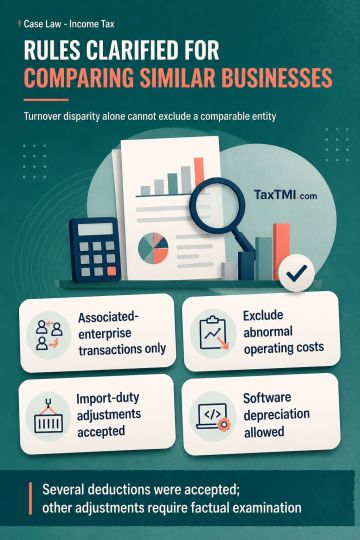
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
Page of 4929
Press 'Enter' after typing page number.
1761 to 1780 of 98580 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
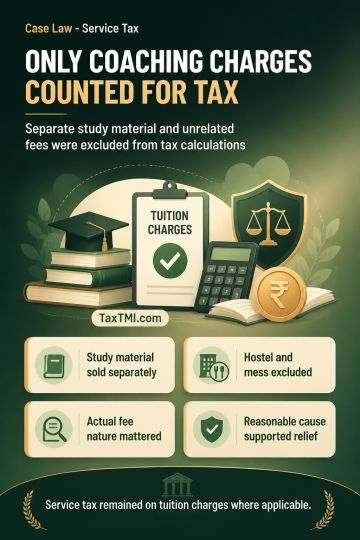
Taxable value of commercial training and coaching excludes separately supplied study material, hostel accommodation, mess facilities and ancillary collections lacking a nexus to coaching. Study material, treated as a distinct sale through separate invoicing and accounting, qualified for the pre-negative-regime exemption where no input credit was availed. Other fees require allocation by their actual nature, with non-taxable components excluded and unresolved allocations re-determined. Receivable entries alone did not establish unpaid tax, and the department had to prove that ancillary income arose from taxable service. Rental to a qualifying educational institution was exempt. Extended limitation failed absent suppression, and reasonable cause supported penalty relief. Service tax remained applicable only to tuition charges where applicable.
Taxable value of commercial training and coaching excludes separately supplied study material, hostel accommodation, mess facilities and ancillary collections lacking a nexus to coaching. Study material, treated as a distinct sale through separate invoicing and accounting, qualified for the pre-negative-regime exemption where no input credit was availed. Other fees require allocation by their actual nature, with non-taxable components excluded and unresolved allocations re-determined. Receivable entries alone did not establish unpaid tax, and the department had to prove that ancillary income arose from taxable service. Rental to a qualifying educational institution was exempt. Extended limitation failed absent suppression, and reasonable cause supported penalty relief. Service tax remained applicable only to tuition charges where applicable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929