Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
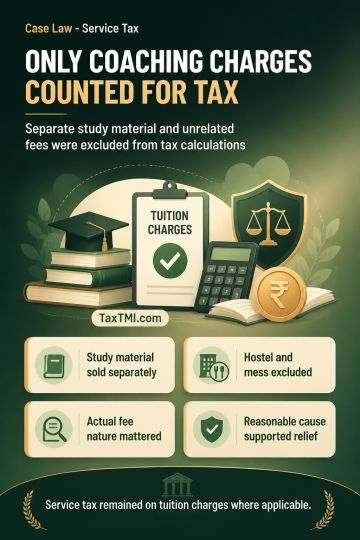
Taxable value of commercial training and coaching excludes separately supplied study material, hostel accommodation, mess facilities and ancillary collections lacking a nexus to coaching. Study material, treated as a distinct sale through separate invoicing and accounting, qualified for the pre-negative-regime exemption where no input credit was availed. Other fees require allocation by their actual nature, with non-taxable components excluded and unresolved allocations re-determined. Receivable entries alone did not establish unpaid tax, and the department had to prove that ancillary income arose from taxable service. Rental to a qualifying educational institution was exempt. Extended limitation failed absent suppression, and reasonable cause supported penalty relief. Service tax remained applicable only to tuition charges where applicable.
Taxable value of commercial training and coaching excludes separately supplied study material, hostel accommodation, mess facilities and ancillary collections lacking a nexus to coaching. Study material, treated as a distinct sale through separate invoicing and accounting, qualified for the pre-negative-regime exemption where no input credit was availed. Other fees require allocation by their actual nature, with non-taxable components excluded and unresolved allocations re-determined. Receivable entries alone did not establish unpaid tax, and the department had to prove that ancillary income arose from taxable service. Rental to a qualifying educational institution was exempt. Extended limitation failed absent suppression, and reasonable cause supported penalty relief. Service tax remained applicable only to tuition charges where applicable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI