Jurisdictional sanction requirements bar reassessment when approval comes from an authority lacking statutory competence under the applicable framewor...
Recorded sales receipts cannot be reassessed as unexplained cash credits, eliminating the basis for consequential alleged commission expenditure addit...
Sufficient cause for delayed income-tax appeals requires bona fide diligence; unsubstantiated counsel illness and assessee inaction defeat condonation...
TNMM Segmentation Limits Transfer-Pricing Adjustments to Associated-Enterprise Transactions and Requires Turnover-Based Comparable Selection for IT Se...
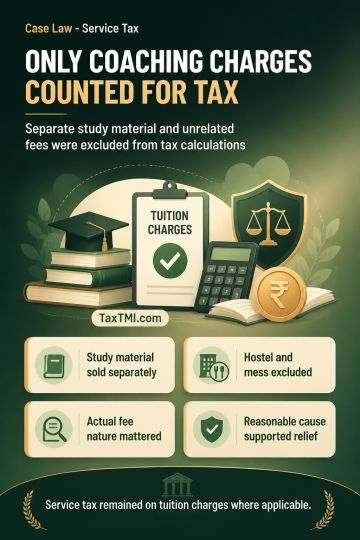
Taxable value of commercial training and coaching excludes separately supplied study material, hostel accommodation, mess facilities and ancillary collections lacking a nexus to coaching. Study material, treated as a distinct sale through separate invoicing and accounting, qualified for the pre-negative-regime exemption where no input credit was availed. Other fees require allocation by their actual nature, with non-taxable components excluded and unresolved allocations re-determined. Receivable entries alone did not establish unpaid tax, and the department had to prove that ancillary income arose from taxable service. Rental to a qualifying educational institution was exempt. Extended limitation failed absent suppression, and reasonable cause supported penalty relief. Service tax remained applicable only to tuition charges where applicable.
Taxable value of commercial training and coaching excludes separately supplied study material, hostel accommodation, mess facilities and ancillary collections lacking a nexus to coaching. Study material, treated as a distinct sale through separate invoicing and accounting, qualified for the pre-negative-regime exemption where no input credit was availed. Other fees require allocation by their actual nature, with non-taxable components excluded and unresolved allocations re-determined. Receivable entries alone did not establish unpaid tax, and the department had to prove that ancillary income arose from taxable service. Rental to a qualifying educational institution was exempt. Extended limitation failed absent suppression, and reasonable cause supported penalty relief. Service tax remained applicable only to tuition charges where applicable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI