Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Development rights transfers treated as immovable property, while construction abatement applies and repeated non-payment permits extended service-tax...
Page of 481
Press 'Enter' after typing page number.
1 to 20 of 9619 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
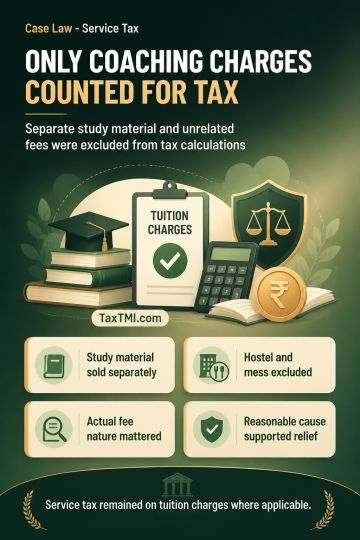
Taxable value of commercial training and coaching excludes separately supplied study material, hostel accommodation, mess facilities and ancillary collections lacking a nexus to coaching. Study material, treated as a distinct sale through separate invoicing and accounting, qualified for the pre-negative-regime exemption where no input credit was availed. Other fees require allocation by their actual nature, with non-taxable components excluded and unresolved allocations re-determined. Receivable entries alone did not establish unpaid tax, and the department had to prove that ancillary income arose from taxable service. Rental to a qualifying educational institution was exempt. Extended limitation failed absent suppression, and reasonable cause supported penalty relief. Service tax remained applicable only to tuition charges where applicable.
Taxable value of commercial training and coaching excludes separately supplied study material, hostel accommodation, mess facilities and ancillary collections lacking a nexus to coaching. Study material, treated as a distinct sale through separate invoicing and accounting, qualified for the pre-negative-regime exemption where no input credit was availed. Other fees require allocation by their actual nature, with non-taxable components excluded and unresolved allocations re-determined. Receivable entries alone did not establish unpaid tax, and the department had to prove that ancillary income arose from taxable service. Rental to a qualifying educational institution was exempt. Extended limitation failed absent suppression, and reasonable cause supported penalty relief. Service tax remained applicable only to tuition charges where applicable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI