Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
Transfer-pricing treatment of ITeS margins excludes pass-through tax recoveries and separate delayed-receivables interest after working-capital adjust...
Capacity-utilisation adjustments under TNMM can neutralise substantiated COVID-related idle costs where underutilisation materially affects profitabil...
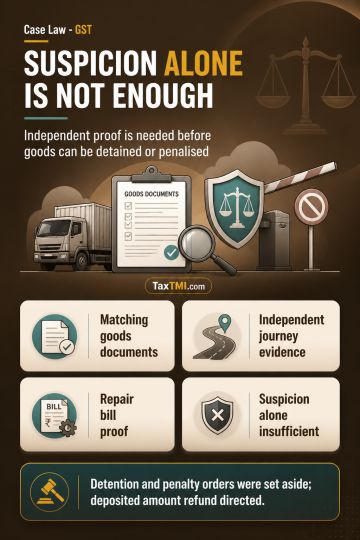
Alleged reuse of an e-way bill cannot justify detention and penalty where the goods are supported by an invoice, e-invoice and e-way bill without discrepancies in description, quantity, value or ownership. Re-transportation must be established by independent, cogent evidence that an earlier journey was completed or the goods were delivered; an inference from prior e-way bill verification alone is insufficient. Intention to evade tax cannot be presumed from suspicion, and the alleged falsity of a vehicle-repair bill must also be proved. The detention and penalty orders were set aside, and refund of the deposited amount was directed in accordance with law.
Alleged reuse of an e-way bill cannot justify detention and penalty where the goods are supported by an invoice, e-invoice and e-way bill without discrepancies in description, quantity, value or ownership. Re-transportation must be established by independent, cogent evidence that an earlier journey was completed or the goods were delivered; an inference from prior e-way bill verification alone is insufficient. Intention to evade tax cannot be presumed from suspicion, and the alleged falsity of a vehicle-repair bill must also be proved. The detention and penalty orders were set aside, and refund of the deposited amount was directed in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886