Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
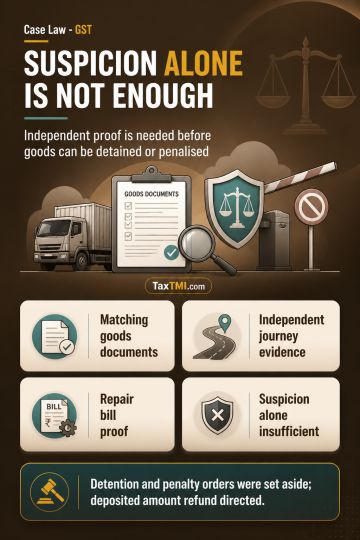
Alleged reuse of an e-way bill cannot justify detention and penalty where the goods are supported by an invoice, e-invoice and e-way bill without discrepancies in description, quantity, value or ownership. Re-transportation must be established by independent, cogent evidence that an earlier journey was completed or the goods were delivered; an inference from prior e-way bill verification alone is insufficient. Intention to evade tax cannot be presumed from suspicion, and the alleged falsity of a vehicle-repair bill must also be proved. The detention and penalty orders were set aside, and refund of the deposited amount was directed in accordance with law.
Alleged reuse of an e-way bill cannot justify detention and penalty where the goods are supported by an invoice, e-invoice and e-way bill without discrepancies in description, quantity, value or ownership. Re-transportation must be established by independent, cogent evidence that an earlier journey was completed or the goods were delivered; an inference from prior e-way bill verification alone is insufficient. Intention to evade tax cannot be presumed from suspicion, and the alleged falsity of a vehicle-repair bill must also be proved. The detention and penalty orders were set aside, and refund of the deposited amount was directed in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886