Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
Alternate statutory remedy governs GST assessment challenge, with statutory appeal preserved and limitation objection barred for the permitted filing ...
Page of 4888
Press 'Enter' after typing page number.
1181 to 1200 of 97752 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
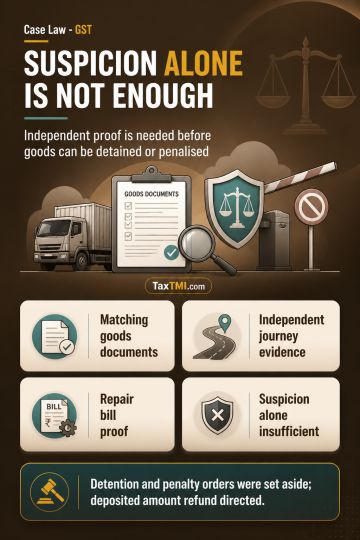
Alleged reuse of an e-way bill cannot justify detention and penalty where the goods are supported by an invoice, e-invoice and e-way bill without discrepancies in description, quantity, value or ownership. Re-transportation must be established by independent, cogent evidence that an earlier journey was completed or the goods were delivered; an inference from prior e-way bill verification alone is insufficient. Intention to evade tax cannot be presumed from suspicion, and the alleged falsity of a vehicle-repair bill must also be proved. The detention and penalty orders were set aside, and refund of the deposited amount was directed in accordance with law.
Alleged reuse of an e-way bill cannot justify detention and penalty where the goods are supported by an invoice, e-invoice and e-way bill without discrepancies in description, quantity, value or ownership. Re-transportation must be established by independent, cogent evidence that an earlier journey was completed or the goods were delivered; an inference from prior e-way bill verification alone is insufficient. Intention to evade tax cannot be presumed from suspicion, and the alleged falsity of a vehicle-repair bill must also be proved. The detention and penalty orders were set aside, and refund of the deposited amount was directed in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888