GST payment representations require record-based, reasoned decisions while substantive entitlement remains open for determination by competent authori...
Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
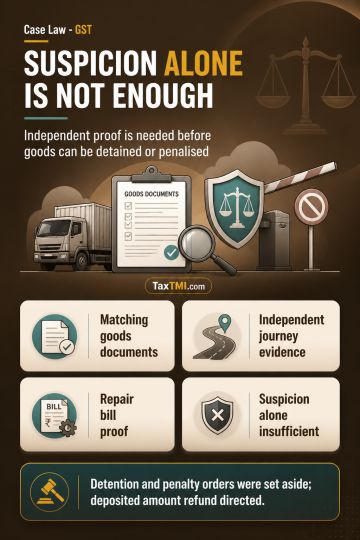
Alleged reuse of an e-way bill cannot justify detention and penalty where the goods are supported by an invoice, e-invoice and e-way bill without discrepancies in description, quantity, value or ownership. Re-transportation must be established by independent, cogent evidence that an earlier journey was completed or the goods were delivered; an inference from prior e-way bill verification alone is insufficient. Intention to evade tax cannot be presumed from suspicion, and the alleged falsity of a vehicle-repair bill must also be proved. The detention and penalty orders were set aside, and refund of the deposited amount was directed in accordance with law.
Alleged reuse of an e-way bill cannot justify detention and penalty where the goods are supported by an invoice, e-invoice and e-way bill without discrepancies in description, quantity, value or ownership. Re-transportation must be established by independent, cogent evidence that an earlier journey was completed or the goods were delivered; an inference from prior e-way bill verification alone is insufficient. Intention to evade tax cannot be presumed from suspicion, and the alleged falsity of a vehicle-repair bill must also be proved. The detention and penalty orders were set aside, and refund of the deposited amount was directed in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888