Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
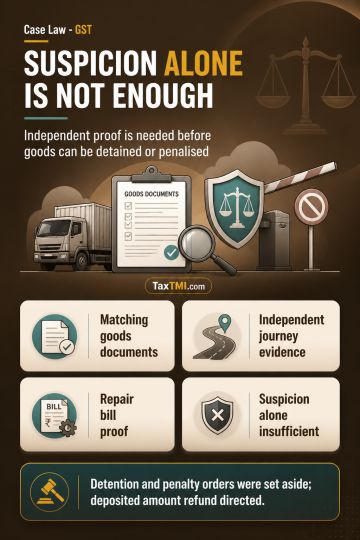
Alleged reuse of an e-way bill cannot justify detention and penalty where the goods are supported by an invoice, e-invoice and e-way bill without discrepancies in description, quantity, value or ownership. Re-transportation must be established by independent, cogent evidence that an earlier journey was completed or the goods were delivered; an inference from prior e-way bill verification alone is insufficient. Intention to evade tax cannot be presumed from suspicion, and the alleged falsity of a vehicle-repair bill must also be proved. The detention and penalty orders were set aside, and refund of the deposited amount was directed in accordance with law.
Alleged reuse of an e-way bill cannot justify detention and penalty where the goods are supported by an invoice, e-invoice and e-way bill without discrepancies in description, quantity, value or ownership. Re-transportation must be established by independent, cogent evidence that an earlier journey was completed or the goods were delivered; an inference from prior e-way bill verification alone is insufficient. Intention to evade tax cannot be presumed from suspicion, and the alleged falsity of a vehicle-repair bill must also be proved. The detention and penalty orders were set aside, and refund of the deposited amount was directed in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918