PMLA anticipatory bail requires satisfaction of twin conditions, while predicate-offence protection does not extend to independent money-laundering pr...
School-affiliation charges remain taxable where not directly connected with examinations, while extended limitation requires proof of deliberate tax e...
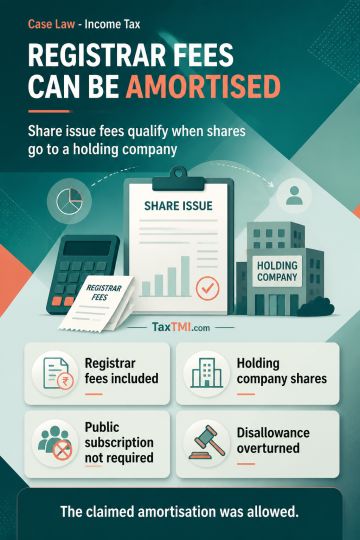
Fees paid to the Registrar of Companies for increasing share capital through shares issued to a holding company qualify for amortisation as preliminary expenditure. The provision covers expenditure incurred in connection with the issue of shares; it is not confined to expenses relating to a public subscription. The enumerated expenses are descriptive, and the comma after "issue" prevents a restrictive reading that would exclude Registrar fees. Accordingly, disallowance of the claimed amortisation was unsustainable, and amortisation of the share-capital issue fees was allowed.
Fees paid to the Registrar of Companies for increasing share capital through shares issued to a holding company qualify for amortisation as preliminary expenditure. The provision covers expenditure incurred in connection with the issue of shares; it is not confined to expenses relating to a public subscription. The enumerated expenses are descriptive, and the comma after "issue" prevents a restrictive reading that would exclude Registrar fees. Accordingly, disallowance of the claimed amortisation was unsustainable, and amortisation of the share-capital issue fees was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888