Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
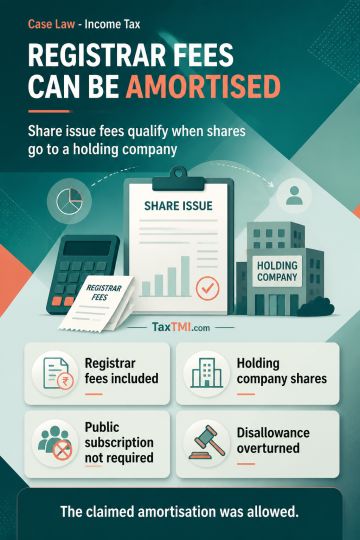
Fees paid to the Registrar of Companies for increasing share capital through shares issued to a holding company qualify for amortisation as preliminary expenditure. The provision covers expenditure incurred in connection with the issue of shares; it is not confined to expenses relating to a public subscription. The enumerated expenses are descriptive, and the comma after "issue" prevents a restrictive reading that would exclude Registrar fees. Accordingly, disallowance of the claimed amortisation was unsustainable, and amortisation of the share-capital issue fees was allowed.
Fees paid to the Registrar of Companies for increasing share capital through shares issued to a holding company qualify for amortisation as preliminary expenditure. The provision covers expenditure incurred in connection with the issue of shares; it is not confined to expenses relating to a public subscription. The enumerated expenses are descriptive, and the comma after "issue" prevents a restrictive reading that would exclude Registrar fees. Accordingly, disallowance of the claimed amortisation was unsustainable, and amortisation of the share-capital issue fees was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI