Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
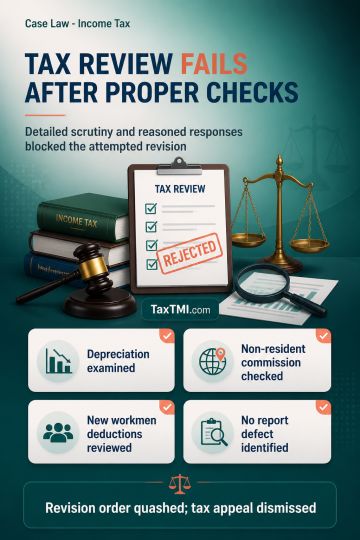
Revision of an assessment for lack of inquiry requires an erroneous and prejudicial order, not merely a different view of matters examined during scrutiny. Where the Assessing Officer made inquiries into depreciation on fixed assets, commission paid to a non-resident, and deductions for employing new workmen, and applied mind to the responses, revision was not sustainable. The Principal Commissioner had identified neither a flaw in the assessee's replies nor a specific defect in the prescribed audit report. The revision order was quashed, and the tax appeal was dismissed because the Tribunal's findings disclosed no legal infirmity.
Revision of an assessment for lack of inquiry requires an erroneous and prejudicial order, not merely a different view of matters examined during scrutiny. Where the Assessing Officer made inquiries into depreciation on fixed assets, commission paid to a non-resident, and deductions for employing new workmen, and applied mind to the responses, revision was not sustainable. The Principal Commissioner had identified neither a flaw in the assessee's replies nor a specific defect in the prescribed audit report. The revision order was quashed, and the tax appeal was dismissed because the Tribunal's findings disclosed no legal infirmity.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886