Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Under TNMM, comparables for an assessee providing ITeS support...
Functional comparability under TNMM supported exclusion of ITeS comparables with R&D, intangibles, diversified operations, or unavailable segmental data.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
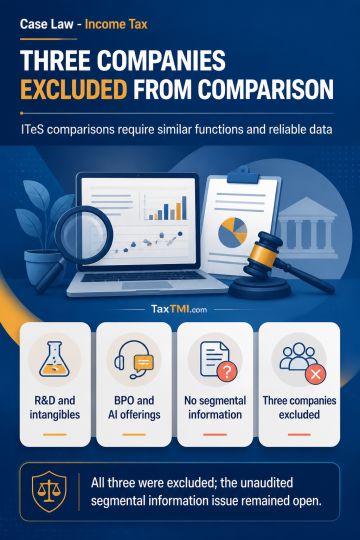
Under TNMM, comparables for an assessee providing ITeS support services to its associated enterprise must be functionally similar and capable of reliable comparison. Tata Elxsi was unsuitable because its design and engineering, digital-content, R&D and software-development activities involved substantial intangibles. TTEC India Customer Solutions was unsuitable because its BPO, technology and AI-enhanced offerings differed from the tested ITeS support services. CHEERS was unsuitable because its mixed ITeS and other operations lacked segmental information. All three were excluded from the final comparable set; the issue of the assessee's unaudited segmental information remained open.
Under TNMM, comparables for an assessee providing ITeS support services to its associated enterprise must be functionally similar and capable of reliable comparison. Tata Elxsi was unsuitable because its design and engineering, digital-content, R&D and software-development activities involved substantial intangibles. TTEC India Customer Solutions was unsuitable because its BPO, technology and AI-enhanced offerings differed from the tested ITeS support services. CHEERS was unsuitable because its mixed ITeS and other operations lacked segmental information. All three were excluded from the final comparable set; the issue of the assessee's unaudited segmental information remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI