Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
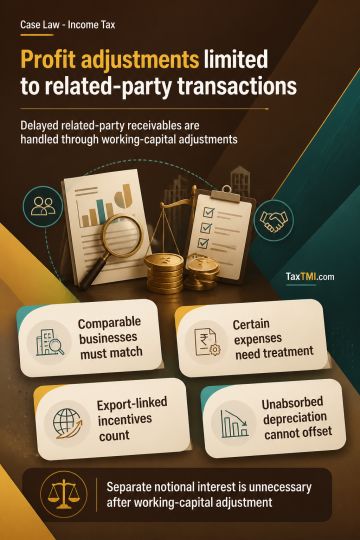
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Taxability of receipts reported in Form 26AS depends on the real nature of the underlying transaction, not solely on the deductor's description of them as commission. Form 26AS reflects deductor-reported TDS information and is not conclusive of the recipient's taxable income. Invoice-wise reconciliation of recharge-voucher purchases and sales may establish that the difference between reported receipts and declared commission represents trade discount. Where the Revenue produces no material disproving that reconciliation or showing the discount to be fictitious, trade discount cannot be assessed as commission income merely because it is reported as such in Form 26AS.
Taxability of receipts reported in Form 26AS depends on the real nature of the underlying transaction, not solely on the deductor's description of them as commission. Form 26AS reflects deductor-reported TDS information and is not conclusive of the recipient's taxable income. Invoice-wise reconciliation of recharge-voucher purchases and sales may establish that the difference between reported receipts and declared commission represents trade discount. Where the Revenue produces no material disproving that reconciliation or showing the discount to be fictitious, trade discount cannot be assessed as commission income merely because it is reported as such in Form 26AS.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927