Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
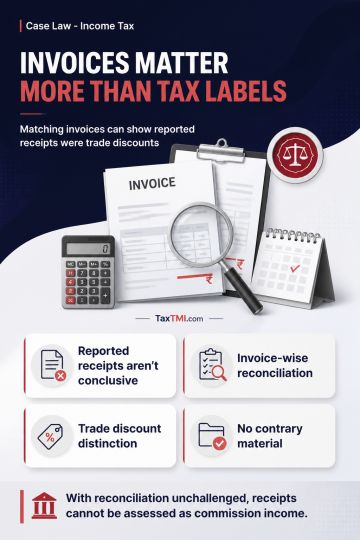
Taxability of receipts reported in Form 26AS depends on the real nature of the underlying transaction, not solely on the deductor's description of them as commission. Form 26AS reflects deductor-reported TDS information and is not conclusive of the recipient's taxable income. Invoice-wise reconciliation of recharge-voucher purchases and sales may establish that the difference between reported receipts and declared commission represents trade discount. Where the Revenue produces no material disproving that reconciliation or showing the discount to be fictitious, trade discount cannot be assessed as commission income merely because it is reported as such in Form 26AS.
Taxability of receipts reported in Form 26AS depends on the real nature of the underlying transaction, not solely on the deductor's description of them as commission. Form 26AS reflects deductor-reported TDS information and is not conclusive of the recipient's taxable income. Invoice-wise reconciliation of recharge-voucher purchases and sales may establish that the difference between reported receipts and declared commission represents trade discount. Where the Revenue produces no material disproving that reconciliation or showing the discount to be fictitious, trade discount cannot be assessed as commission income merely because it is reported as such in Form 26AS.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI