Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
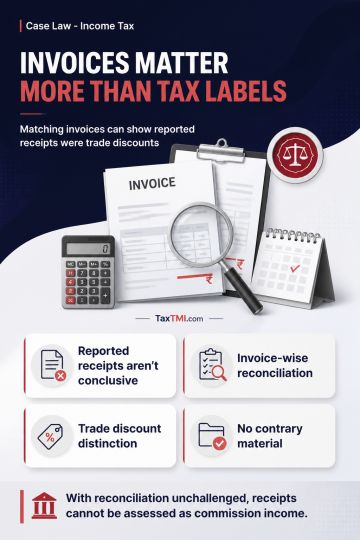
Taxability of receipts reported in Form 26AS depends on the real nature of the underlying transaction, not solely on the deductor's description of them as commission. Form 26AS reflects deductor-reported TDS information and is not conclusive of the recipient's taxable income. Invoice-wise reconciliation of recharge-voucher purchases and sales may establish that the difference between reported receipts and declared commission represents trade discount. Where the Revenue produces no material disproving that reconciliation or showing the discount to be fictitious, trade discount cannot be assessed as commission income merely because it is reported as such in Form 26AS.
Taxability of receipts reported in Form 26AS depends on the real nature of the underlying transaction, not solely on the deductor's description of them as commission. Form 26AS reflects deductor-reported TDS information and is not conclusive of the recipient's taxable income. Invoice-wise reconciliation of recharge-voucher purchases and sales may establish that the difference between reported receipts and declared commission represents trade discount. Where the Revenue produces no material disproving that reconciliation or showing the discount to be fictitious, trade discount cannot be assessed as commission income merely because it is reported as such in Form 26AS.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894