Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Page of 4888
Press 'Enter' after typing page number.
1321 to 1340 of 97750 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
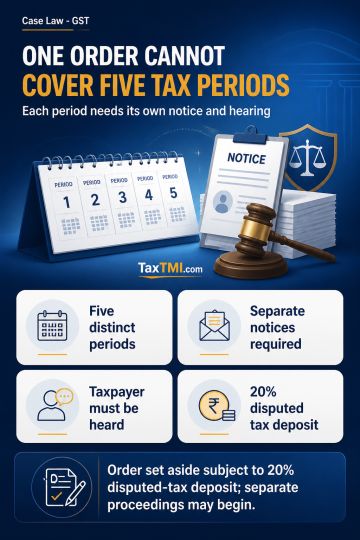
Composite GST assessment orders covering five distinct tax periods are unsustainable. Separate notices must be issued for each respective tax period, and the taxpayer must receive an opportunity of hearing before fresh assessment action is taken. The High Court declined to examine the assessment merits and set aside the composite order, subject to deposit of 20% of the disputed tax within the stipulated period. On default, the authorities may proceed in accordance with law. Fresh proceedings may be initiated separately for each tax period.
Composite GST assessment orders covering five distinct tax periods are unsustainable. Separate notices must be issued for each respective tax period, and the taxpayer must receive an opportunity of hearing before fresh assessment action is taken. The High Court declined to examine the assessment merits and set aside the composite order, subject to deposit of 20% of the disputed tax within the stipulated period. On default, the authorities may proceed in accordance with law. Fresh proceedings may be initiated separately for each tax period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888