Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
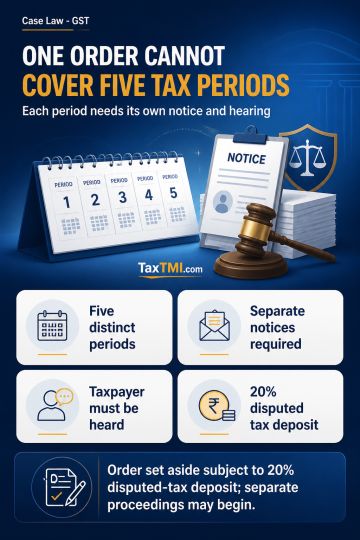
Composite GST assessment orders covering five distinct tax periods are unsustainable. Separate notices must be issued for each respective tax period, and the taxpayer must receive an opportunity of hearing before fresh assessment action is taken. The High Court declined to examine the assessment merits and set aside the composite order, subject to deposit of 20% of the disputed tax within the stipulated period. On default, the authorities may proceed in accordance with law. Fresh proceedings may be initiated separately for each tax period.
Composite GST assessment orders covering five distinct tax periods are unsustainable. Separate notices must be issued for each respective tax period, and the taxpayer must receive an opportunity of hearing before fresh assessment action is taken. The High Court declined to examine the assessment merits and set aside the composite order, subject to deposit of 20% of the disputed tax within the stipulated period. On default, the authorities may proceed in accordance with law. Fresh proceedings may be initiated separately for each tax period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI