Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
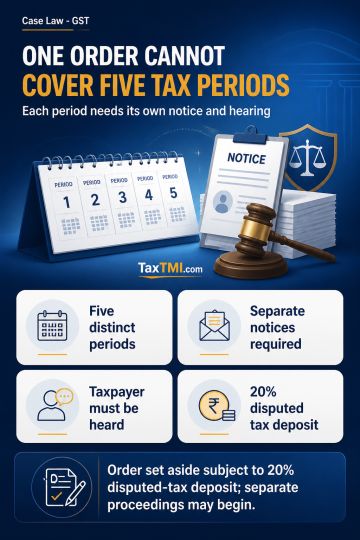
Composite GST assessment orders covering five distinct tax periods are unsustainable. Separate notices must be issued for each respective tax period, and the taxpayer must receive an opportunity of hearing before fresh assessment action is taken. The High Court declined to examine the assessment merits and set aside the composite order, subject to deposit of 20% of the disputed tax within the stipulated period. On default, the authorities may proceed in accordance with law. Fresh proceedings may be initiated separately for each tax period.
Composite GST assessment orders covering five distinct tax periods are unsustainable. Separate notices must be issued for each respective tax period, and the taxpayer must receive an opportunity of hearing before fresh assessment action is taken. The High Court declined to examine the assessment merits and set aside the composite order, subject to deposit of 20% of the disputed tax within the stipulated period. On default, the authorities may proceed in accordance with law. Fresh proceedings may be initiated separately for each tax period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918