Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
Alternate statutory remedy governs GST assessment challenge, with statutory appeal preserved and limitation objection barred for the permitted filing ...
Page of 4927
Press 'Enter' after typing page number.
1961 to 1980 of 98535 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Annual Production Capacity determination under the applicable...
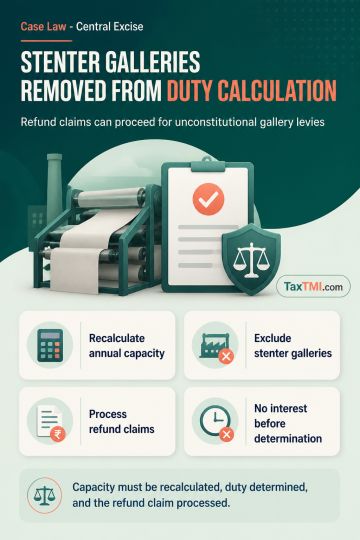
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment bar.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Annual Production Capacity determination under the applicable rules is an administrative exercise rather than an appealable order; failure to challenge it therefore does not bar a refund claim. Duty imposed on stenter galleries, being unconstitutional, must be excluded when capacity is redetermined. The unjust-enrichment bar and refund provisions governing duty recovery do not apply where the levy itself was unconstitutional. Annual Production Capacity must be recalculated excluding galleries, consequential duty determined, and the refund claim processed. No interest is payable until the refund claim is determined. Questions concerning rectification applications remain unanswered.
Annual Production Capacity determination under the applicable rules is an administrative exercise rather than an appealable order; failure to challenge it therefore does not bar a refund claim. Duty imposed on stenter galleries, being unconstitutional, must be excluded when capacity is redetermined. The unjust-enrichment bar and refund provisions governing duty recovery do not apply where the levy itself was unconstitutional. Annual Production Capacity must be recalculated excluding galleries, consequential duty determined, and the refund claim processed. No interest is payable until the refund claim is determined. Questions concerning rectification applications remain unanswered.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927