Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Annual Production Capacity determination under the applicable...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment bar.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
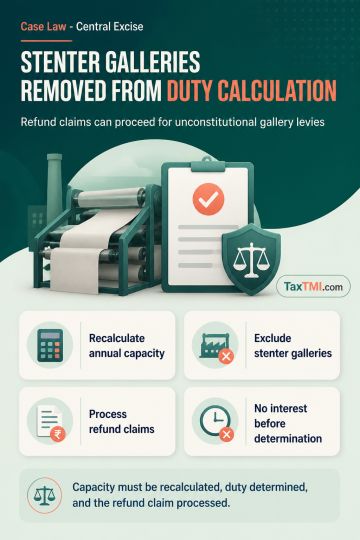
Annual Production Capacity determination under the applicable rules is an administrative exercise rather than an appealable order; failure to challenge it therefore does not bar a refund claim. Duty imposed on stenter galleries, being unconstitutional, must be excluded when capacity is redetermined. The unjust-enrichment bar and refund provisions governing duty recovery do not apply where the levy itself was unconstitutional. Annual Production Capacity must be recalculated excluding galleries, consequential duty determined, and the refund claim processed. No interest is payable until the refund claim is determined. Questions concerning rectification applications remain unanswered.
Annual Production Capacity determination under the applicable rules is an administrative exercise rather than an appealable order; failure to challenge it therefore does not bar a refund claim. Duty imposed on stenter galleries, being unconstitutional, must be excluded when capacity is redetermined. The unjust-enrichment bar and refund provisions governing duty recovery do not apply where the levy itself was unconstitutional. Annual Production Capacity must be recalculated excluding galleries, consequential duty determined, and the refund claim processed. No interest is payable until the refund claim is determined. Questions concerning rectification applications remain unanswered.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI