Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
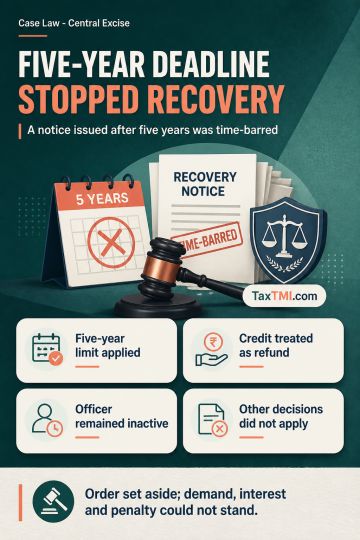
Recovery of irregular or excess suo motu credit under Notification No. 39/2001-CE is treated as recovery of excise duty erroneously refunded where the credit is not reversed. The limitation applicable to erroneous refunds therefore governs such recovery. A recovery notice issued more than five years after credit was taken was time-barred, rendering the related demand, interest and penalty unsustainable. Annual differential-duty credit taken after submission of the prescribed statement and prolonged inaction by the jurisdictional officer was treated as compliant with the notification. Revenue authorities' cited decisions on different forms of suo motu adjustment or refund did not apply. The impugned order was consequently set aside.
Recovery of irregular or excess suo motu credit under Notification No. 39/2001-CE is treated as recovery of excise duty erroneously refunded where the credit is not reversed. The limitation applicable to erroneous refunds therefore governs such recovery. A recovery notice issued more than five years after credit was taken was time-barred, rendering the related demand, interest and penalty unsustainable. Annual differential-duty credit taken after submission of the prescribed statement and prolonged inaction by the jurisdictional officer was treated as compliant with the notification. Revenue authorities' cited decisions on different forms of suo motu adjustment or refund did not apply. The impugned order was consequently set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI