Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
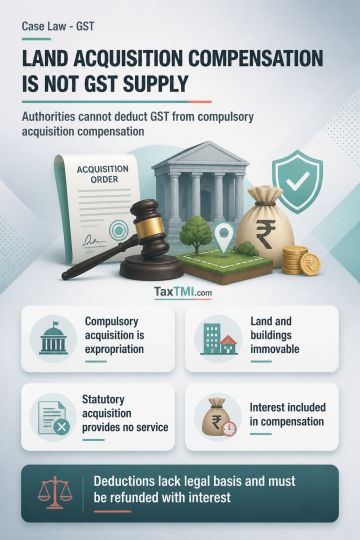
Compulsory acquisition of land and attached structures under eminent-domain powers is an expropriation, not a supply of goods or services for GST purposes. Land and buildings are immovable property and cannot be treated as goods, while a landowner does not provide any service through statutory acquisition. GST deducted from acquisition compensation therefore lacks statutory basis, is beyond the acquiring authority's power, and must be refunded with interest. Interest awarded on compensation under the Land Acquisition Act to account for the period until payment forms part of compensation and is not subject to tax deduction at source.
Compulsory acquisition of land and attached structures under eminent-domain powers is an expropriation, not a supply of goods or services for GST purposes. Land and buildings are immovable property and cannot be treated as goods, while a landowner does not provide any service through statutory acquisition. GST deducted from acquisition compensation therefore lacks statutory basis, is beyond the acquiring authority's power, and must be refunded with interest. Interest awarded on compensation under the Land Acquisition Act to account for the period until payment forms part of compensation and is not subject to tax deduction at source.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI