Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
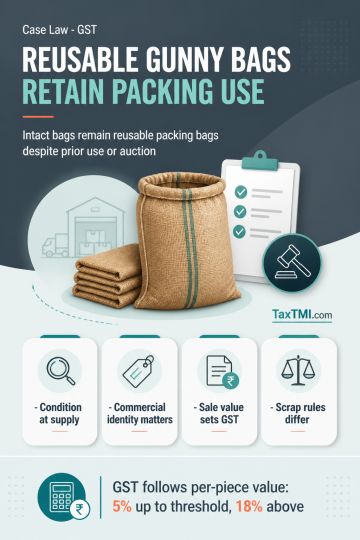
Used jute gunny bags without plastic coating remain classifiable as reusable packing bags under Heading 6305 where they are intact, identifiable and fit for repacking agricultural produce. Classification turns on the goods' condition, essential character, commercial identity and functional utility at supply; prior use or auction sale does not by itself convert them into scrap. Worn sacks and bags fall outside Heading 6309, while Heading 6310 applies only to worn-out textile materials fit solely for recovery. GST is determined by sale value per piece: 5% up to the prescribed threshold and 18% above it. Torn, worn-out or cut bags unfit for reuse require separate classification examination.
Used jute gunny bags without plastic coating remain classifiable as reusable packing bags under Heading 6305 where they are intact, identifiable and fit for repacking agricultural produce. Classification turns on the goods' condition, essential character, commercial identity and functional utility at supply; prior use or auction sale does not by itself convert them into scrap. Worn sacks and bags fall outside Heading 6309, while Heading 6310 applies only to worn-out textile materials fit solely for recovery. GST is determined by sale value per piece: 5% up to the prescribed threshold and 18% above it. Torn, worn-out or cut bags unfit for reuse require separate classification examination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI