Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Valid exercise of the concessional corporate tax option through...
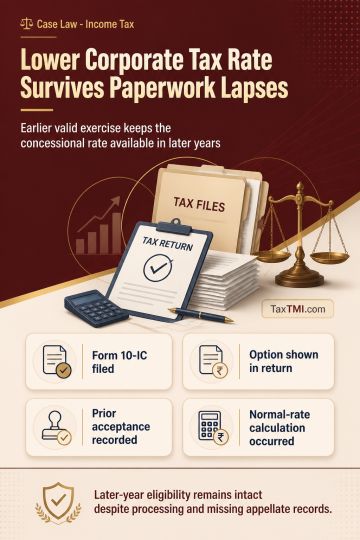
Concessional corporate tax option under section 115BAA survives procedural documentary lapses when statutory compliance and earlier exercise are established.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Valid exercise of the concessional corporate tax option through Form No. 10-IC under section 115BAA continues to apply in subsequent assessment years. Filing the prescribed form, disclosing the option in the relevant return, and prior departmental acceptance support the continuing availability of the concessional rate. Computation at the normal rate during return processing or failure to submit supporting records at the first appellate stage does not negate substantive eligibility where statutory compliance is otherwise established.
Valid exercise of the concessional corporate tax option through Form No. 10-IC under section 115BAA continues to apply in subsequent assessment years. Filing the prescribed form, disclosing the option in the relevant return, and prior departmental acceptance support the continuing availability of the concessional rate. Computation at the normal rate during return processing or failure to submit supporting records at the first appellate stage does not negate substantive eligibility where statutory compliance is otherwise established.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI