Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
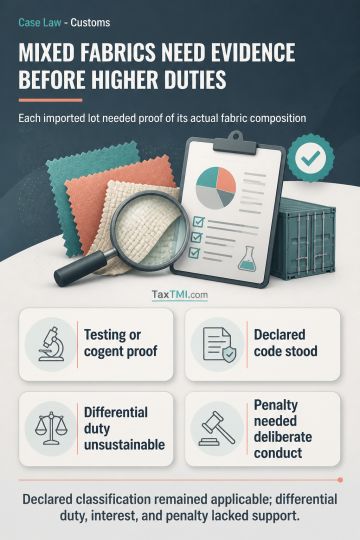
Tariff classification of imported mixed lots of polyester knitted fabrics requires evidence of the actual composition of goods covered by each Bill of Entry. A description as "polyester knitted fabric" does not, without testing or other cogent evidence, establish the characteristics needed to reclassify mixed assorted fabrics as fabrics of synthetic fibres. The declared classification under CTH 6006 9000 remained applicable, and the proposed classification under CTH 6006 3200, with differential duty and interest, was unsustainable. Penalty for misclassification also required proof of deliberate suppression, wilful misstatement, or intent to evade duty; an interpretational classification dispute did not establish those elements.
Tariff classification of imported mixed lots of polyester knitted fabrics requires evidence of the actual composition of goods covered by each Bill of Entry. A description as "polyester knitted fabric" does not, without testing or other cogent evidence, establish the characteristics needed to reclassify mixed assorted fabrics as fabrics of synthetic fibres. The declared classification under CTH 6006 9000 remained applicable, and the proposed classification under CTH 6006 3200, with differential duty and interest, was unsustainable. Penalty for misclassification also required proof of deliberate suppression, wilful misstatement, or intent to evade duty; an interpretational classification dispute did not establish those elements.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI