Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Customs Assessment Portal centralises classification and valuation guidance to support consistent, transparent and informed compliance across stakehol...
GST refunds for cancelled air tickets remain available when passenger reimbursements defeat unjust enrichment and credit-note adjustment is unavailabl...
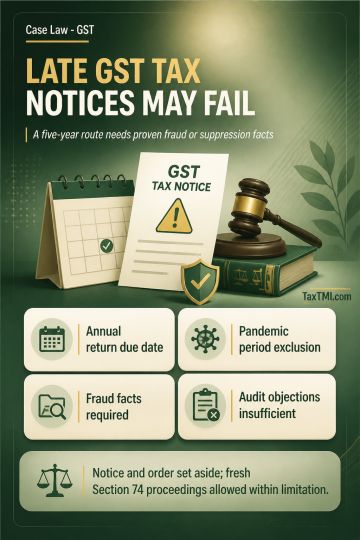
GST demand limitation under Section 73 runs from the due date for the annual return; extensions of those due dates change its commencement, and pandemic-period exclusion must be applied when calculating the three-year period. A notice issued after the resulting deadline cannot be sustained under the ordinary limitation. Recourse to Section 74's five-year period requires the Assessing Officer's satisfaction, based on disclosed foundational facts, that fraud, wilful misstatement or suppression caused the tax shortfall or excess input tax credit. Audit objections and bare statutory assertions are insufficient. The show-cause notice and consequential order were set aside, with liberty for fresh Section 74 proceedings within the applicable extended limitation.
GST demand limitation under Section 73 runs from the due date for the annual return; extensions of those due dates change its commencement, and pandemic-period exclusion must be applied when calculating the three-year period. A notice issued after the resulting deadline cannot be sustained under the ordinary limitation. Recourse to Section 74's five-year period requires the Assessing Officer's satisfaction, based on disclosed foundational facts, that fraud, wilful misstatement or suppression caused the tax shortfall or excess input tax credit. Audit objections and bare statutory assertions are insufficient. The show-cause notice and consequential order were set aside, with liberty for fresh Section 74 proceedings within the applicable extended limitation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915