Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
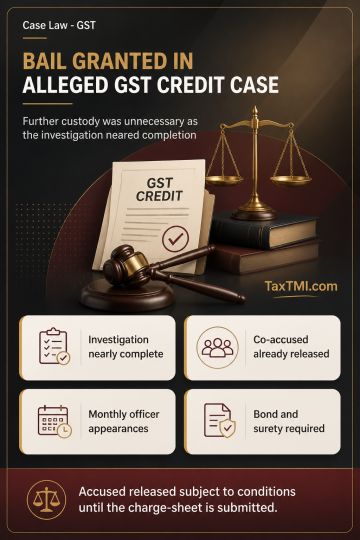
Bail was granted to an accused alleged to have operated a firm used for fraudulent availment of input tax credit, although the firm was registered in his spouse's name. The High Court treated the investigation concerning the accused as almost complete and considered that certain co-accused had already received bail. Balancing the detention period against the nature and gravity of the allegations, it found that further custodial detention was unnecessary for the investigation. Release was subject to a bond and surety, monthly appearance before the Investigating Officer, and compliance until submission of the charge-sheet.
Bail was granted to an accused alleged to have operated a firm used for fraudulent availment of input tax credit, although the firm was registered in his spouse's name. The High Court treated the investigation concerning the accused as almost complete and considered that certain co-accused had already received bail. Balancing the detention period against the nature and gravity of the allegations, it found that further custodial detention was unnecessary for the investigation. Release was subject to a bond and surety, monthly appearance before the Investigating Officer, and compliance until submission of the charge-sheet.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI